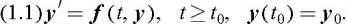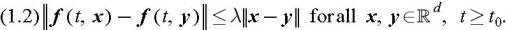A First Course in the Numerical Analysis of Differential Equations, Second Edition

Part I: Ordinary Differential Equations

Chapter List

Chapter 1: Euler s Method and Beyond
Chapter 2: Multistep Methods
Chapter 3: Runge Kutta Methods
Chapter 4: Stiff Equations
Chapter 5: Geometric Numerical Integration
Chapter 6: Error Control
Chapter 7: Nonlinear algebraic systems

1.1 Ordinary Differential Equations and the Lipschitz Condition

We commence our exposition of the computational aspects of differential equations by examining closely numerical methods for ordinary differential equations (ODEs). This is important because of the central role of ODEs in a multitude of applications. Not less crucial is the critical part that numerical ODEs play in the design and analysis of computational methods for partial differential equations (PDEs). Thus, even if your main interest is in solving PDEs, ideally you should first master computational ODEs, not just to familiarize yourself with concepts, terminology and ideas but also because (as we will see in what follows) many discretization methods for PDEs reduce the underlying problem to the computation of ODEs.

Our goal is to approximate the solution of the problem


Here f is a sufficiently well-behaved function that maps [ t 0, ?) to and the initial condition y 0 ? is a given vector; denotes here and elsewhere in this book the d-dimensional real Euclidean space.

The niceness of f may span a whole range of desirable attributes. At the very least, we insist on f obeying, in a given vector norm , the Lipschitz condition


Here ?

UNLIMITED FREE
ACCESS
TO THE WORLD'S BEST IDEAS

SUBMIT
Already a GlobalSpec user? Log in.

This is embarrasing...

An error occurred while processing the form. Please try again in a few minutes.

Customize Your GlobalSpec Experience

Category: Computational Fluid Dynamics Software (CFD)
Finish!
Privacy Policy

This is embarrasing...

An error occurred while processing the form. Please try again in a few minutes.