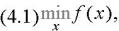Modeling and Simulation in Scilab/Scicos
Chapter 4: Optimization

Various optimization problems play a fundamental role in modeling and simulation. This chapter will cover some of the optimization utilities available in Scilab. Section 4.1 will present some overview comments about optimization, useful in using the algorithms. Section 4.2 discusses the most general optimization utilities. There is a close relationship between optimization and solving equations in a least squares sense. This is examined in Section 4.4. One application of optimization is parameter fitting. Specialized utilities for this are given in Section 4.5. Finally, some specialized optimization utilities for linear and quadratic programming are given in Section 4.6.

4.1 Comments on Optimization and Solving Nonlinear Equations

In this chapter we discuss the problem of solving the minimization problem


where f is a real-valued function of the vector variable x. Note that maximizing f is the same as minimizing f, so that all of the utilities given here can also be used with maximization problems.

There are a number of characteristics of (4.1) that determine which, of any, of the available utilities will work. They also affect how the optional parameters should be set if a simple call does not work.

Constraints

The first question is whether there are any restrictions on x (4.1). if there are, the problem is said to be constrained. As far as Scilab is concerned there are three types of constraints.

Bound, or box, constraints require different entries of x to lie in specified intervals. For example, if x

UNLIMITED FREE
ACCESS
TO THE WORLD'S BEST IDEAS

SUBMIT
Already a GlobalSpec user? Log in.

This is embarrasing...

An error occurred while processing the form. Please try again in a few minutes.

Customize Your GlobalSpec Experience

Category: Website Development and Optimization Services
Finish!
Privacy Policy

This is embarrasing...

An error occurred while processing the form. Please try again in a few minutes.