Risk Analysis in Theory and Practice
Presenting a mix of conceptual analyses and applied problems, this book provides useful insights into the economic rationality of decision-making under uncertainty.
 TABLE OF CONTENTS
Chapter 2 developed the arguments that risk can be assessed using probability measures, i.e., that the relevant probabilities can be estimated empirically using sample information and/or subjective assessments. In this chapter, we assume that the probabilities of risky events have been estimated. Chapter 3 developed a formal theory of decision-making under risk: the expected utility model. In the expected utility model, each decision-maker has a utility function representing his/her risk preferences. In this chapter, we examine the nature of risk preferences. For simplicity, we focus our attention on the case of risky monetary rewards. In this context, we establish formal relationships between the properties of the utility function and risk preferences. This will provide some useful insights in the empirical analysis of risk behavior.
First, we present some mathematical results that will prove useful in our analysis. A key concept is the concavity (or convexity) of a function. A function U( a) is said to be a concave function, if for any ?, 0 < ? < 1, and any two points a 1 and a 2,
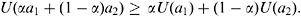
And U( a) is a convex function, if for any ?, 0 < ? < 1, and any two points a 1 and a 2,
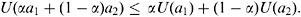
These definitions apply to a general function U( a), whether it is differentiable or not. However, if we also know that the function U( a) is twice continuously differentiable, then