Introduction to Stochastic Calculus with Applications, Second Edition
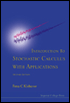
Containing many solved examples and exercises, this book gives a simple but rigorous treatment of stochastic calculus and its applications, including a range of advanced topics.
 TABLE OF CONTENTS
Money invested for different terms T yield a different return corresponding to the rate of interest R( T). This function is called the yield curve, or the term structure of interest rates. Every day this curve changes, the time t curve denoted by R( t, T). However, the rates are not traded directly, they are derived from prices of bonds traded on the bond market. This leads to construction of models for bonds and no-arbitrage pricing for bonds and their options. We present the main models used in the literature and in applications, treating in detail the Merton, Vasicek's, Heath-Jarrow-Morton (HJM) and Brace-Gatarek-Musiela (BGM) models. In our treatment we concentrate on the main mathematical techniques used in such models without going into details of their calibration.
A $1 bond with maturity T is a contract that guarantees the holder $1 at T. Sometimes bonds also pay a certain amount, called a coupon, during the life of the bond, but for the theory it suffices to consider only bonds without coupons (zero-coupon bonds). Denote by P( t, T) the price at time t of the bond paying $1 at T, P( T, T) = 1. The yield to maturity of the bond is defined as
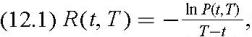
and as a function in T, is called the yield curve at time t. Assume also that a savings account paying at t instantaneous rate