Commercial Awareness and Business Decision Making Skills
The concept of asset revaluation draws us to one of the longest and most contentious arguments in the world of accounting. Is it better to use historic assets values (i.e. those that applied at the date of acquisition) or current market values?

Inflation is a familiar concept that often makes the headlines on television or is a point of conversation as people discuss the cost of living, and it is the fact that historic cost accounting ignores inflation that undermines its credibility as a method for preparing financial information.
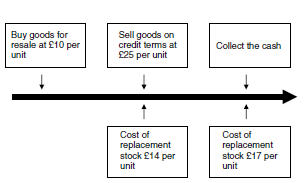
Current revenues are not matched to current costs leading to an overstatement of profits in real terms.

Using historic cost accounting a profit of 15 will be recorded on each unit sold, but at the date of sale 14 will be needed to replace the stock sold. If the company wants to continue trading without recourse to additional funding the real terms profit is 11. It should be noted that in...